
Key facts at a glance
This Shelton guide is part of our series on how to sell a house in Connecticut. It covers one kind of foreclosure help: the court’s free Foreclosure Mediation Program, as it works for a Shelton homeowner with a mortgage foreclosure case.
| Fact | Number | Source |
|---|---|---|
| Deadline to ask for mediation | 15 days after the return date | CGS 49-31l(c); jud.ct.gov homeowner FAQ |
| Court that hears a Shelton foreclosure | Superior Court, Ansonia-Milford judicial district (in Milford) | CGS 51-344, 51-345(b) |
| Lender’s document package due | By day 35 after the return date | CGS 49-31l(c) |
| Mediation period ends | After 3 sessions or 7 months from the return date, whichever is first (court can extend) | CGS 49-31n(a) |
| Most lawsuit motions on hold | Up to 8 months from the return date | CGS 49-31l(f) |
| Shelton median single-family sale price, Oct 2024 to Sep 2025 | $546,500 (536 residential sales) | CT OPM Real Estate Sales, data.ct.gov |
| Shelton mill rate, fiscal 2027 | 15.51 mills (about $5,930 a year on $546,500) | CT OPM mill rates; CGS 12-62a |
| Cost to apply for mediation | $0 | jud.ct.gov homeowner FAQ |
Why does foreclosure mediation feel so confusing when you live in Shelton?
Foreclosure mediation feels confusing in Shelton because the papers come from a court in Milford, not Bridgeport, the forms use legal words, and the deadline to ask for mediation is only 15 days after a return date most people have never heard of. Shelton homeowners at this point often feel ashamed, rushed, distrustful of the bank, and unsure whether mediation is real help or a delay.
Shelton is in Fairfield County, but its court is the Ansonia-Milford judicial district (CGS 51-344), not Bridgeport.
If you have a stack of foreclosure papers on the kitchen table, a lender who stopped calling back, and a feeling that you have already lost, this page is for you. You probably feel ashamed, even though job loss, illness and divorce cause most defaults. You feel trapped by a calendar you cannot read. You may feel skeptical that a court program will help, exhausted by paperwork, and, somewhere underneath, cautiously hopeful because someone mentioned the word “mediation”.
That hope is reasonable. I am Jerryll Noorden; I buy houses in Connecticut, about ten a year since 2016. If you can keep your Shelton house, mediation is usually where that happens, and it is free.
What is foreclosure mediation in Shelton, CT, and who is eligible?
Foreclosure mediation in Shelton, CT is the Connecticut Judicial Branch’s free Ezequiel Santiago Foreclosure Mediation Program (CGS 49-31k to 49-31o). A trained court mediator meets you and your lender’s representative to look for a deal. You are eligible if you signed the mortgage note, own and live in the house as your primary residence, it has one to four units, and it is a mortgage foreclosure.
The rules come from the statute and the court’s own homeowner FAQ. In plain English:
- You must be the borrower and an owner-occupant. The house must be your primary residence and a one- to four-family home in Connecticut (CGS 49-31k(1)).
- Some non-borrowers qualify. A surviving spouse who became sole owner, or a spouse or ex-spouse who got the house in a divorce, can be a “permitted successor-in-interest” for cases with return dates on or after October 1, 2015 (CGS 49-31k(9)).
- The case must be a mortgage foreclosure. The court’s FAQ is direct: cases to foreclose a condominium lien or a tax lien are not eligible. If that is your situation, see our guides on condo association foreclosure and property tax foreclosure.
- A case must already be filed. Before the lawsuit, the free help is a housing counselor and CHFA’s programs; see our guide on being behind on mortgage payments in Connecticut.
Mediators are Judicial Branch employees; they do not represent either side or give legal advice. You do not need a lawyer to take part.
How do you ask for foreclosure mediation in Shelton before the deadline?
You ask for foreclosure mediation in Shelton by filing two forms with the Superior Court clerk for the Ansonia-Milford judicial district no later than 15 days after the return date on your summons: an Appearance (JD-CL-12) and a Foreclosure Mediation Certificate (JD-CV-108). Send a copy to the lender’s attorney. Both forms come attached to the papers the marshal served.
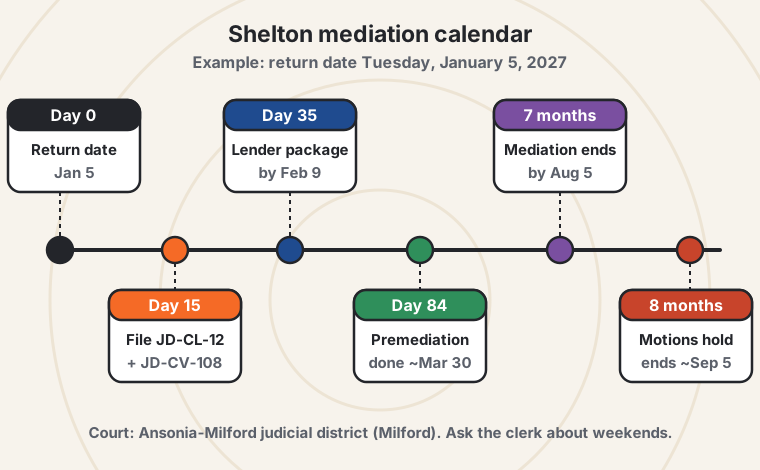
The return date is a Tuesday printed on the summons, not a court date. Our guide to the foreclosure summons in Connecticut shows how to find it and file the forms.
Here is the same calendar as a table, using an example return date. Dates are simple day counts; ask the clerk if a deadline falls on a weekend or holiday.
| Step | Rule | Example (return date Tue, Jan 5, 2027) |
|---|---|---|
| File Appearance (JD-CL-12) and Mediation Certificate (JD-CV-108) | Within 15 days of the return date (CGS 49-31l(c)) | By Wed, Jan 20, 2027 |
| Lender sends you and the mediator its package of forms and loan history | Not later than day 35 (CGS 49-31l(c)) | By Tue, Feb 9, 2027 |
| Premediation meeting with the mediator only | About 2 weeks after the package; usually ends by day 84 (jud.ct.gov FAQ) | Around Mar 30, 2027 |
| Mediation sessions with the lender | Up to 3 sessions or 7 months from the return date, whichever is first (CGS 49-31n(a)) | Ends by Thu, Aug 5, 2027 unless extended |
| Most motions frozen; no judgment until mediation ends | Up to 8 months from the return date (CGS 49-31l(f)) | To about Sep 5, 2027 |
Ask a judge with JD-CV-96 (Part I) plus the JD-CV-108 and an appearance. If mediation ended, JD-CV-136 asks to come back in.
What should a Shelton homeowner bring to foreclosure mediation?
A Shelton homeowner should bring the forms and documents the lender asked for in its day-35 package, completed and copied, plus updated pay stubs, bank statements and anything the mediator requested. Most lenders ask for proof of income, two years of tax returns, a hardship letter, a monthly budget and a recent mortgage statement. Incomplete paperwork is the most common reason mediation stalls.
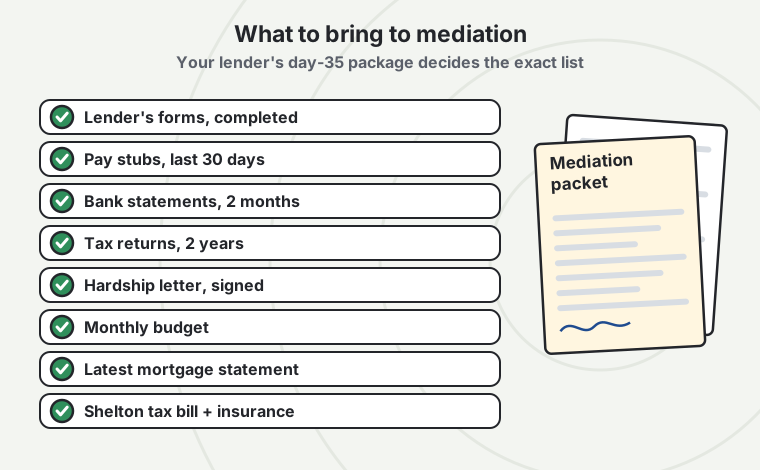
The court’s FAQ is specific about the first part: bring what you completed in premediation and delivered to the bank, plus updated pay stubs, bank statements and anything else the mediator suggested. The rest of this checklist is what lenders typically request. Your lender’s package controls.
- The lender’s forms from the day-35 package, filled in, signed and copied
- Pay stubs for the last 30 days (or benefit letters, pension or Social Security statements)
- The last two months of bank statements, every page
- Two years of federal tax returns, with all schedules
- A short, signed hardship letter: what happened, when, and what has changed
- A monthly budget showing what you can pay now
- Your latest mortgage statement and any letters from the servicer
- Your Shelton property tax bill and homeowners insurance declarations page
Keep a log of every call and upload with the date and the name of the person. The mediator’s reports go into the public court file; your personal financial information does not.
What can come out of foreclosure mediation for a Shelton house?
Foreclosure mediation for a Shelton house can end in a way to keep the home (reinstatement, a repayment plan or a loan modification) or a “graceful exit” (a sale, a short sale or a deed in lieu), or in an agreed Law Day or sale date. Mediation does not stop the foreclosure by itself. If no agreement is reached, the case goes back to court when the mediation period ends.
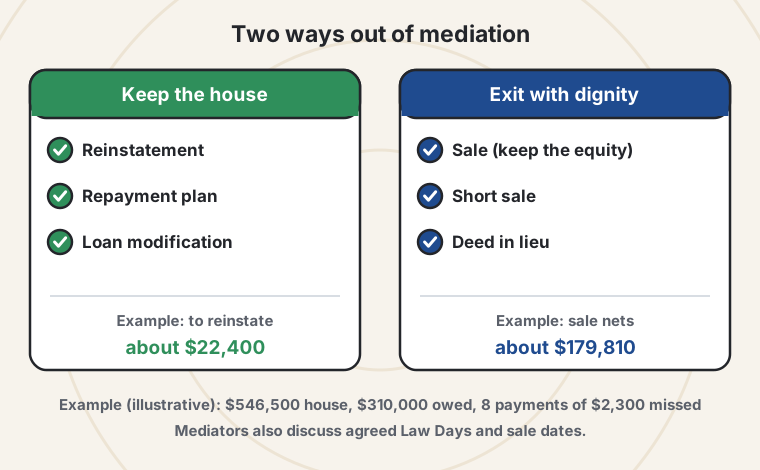
The court’s FAQ lists the topics mediators cover: reinstatements, repayment plans, loan modifications, sales, short sales, deeds in lieu of foreclosure, and the assignment of Law Days and sale dates. A reinstatement fits when the hardship is over and you have the cash; a repayment plan when income is back; a modification when income is lower for good; a sale when you have equity but the payment will not work long term.
Short sales and deeds in lieu have their own guides: short sale vs. foreclosure in Connecticut and deed in lieu of foreclosure.
What does keeping or selling look like with Shelton numbers?
With Shelton numbers, keeping or selling looks like this in our example: a homeowner who owes $310,000 and is eight months behind on a $2,300 payment needs about $22,400 to reinstate, while a sale of a house at Shelton’s $546,500 single-family median would leave about $179,810 after costs and the full payoff. Shelton’s low 15.51 mill rate helps keep a modified payment affordable.
Example (illustrative). The inputs are labeled; your numbers will differ.
| Line | Amount | Basis |
|---|---|---|
| Value of the house | $546,500 | Shelton single-family median, Oct 2024 to Sep 2025 (CT OPM) |
| Loan balance | $310,000 | Assumption |
| Missed payments (8 x $2,300) | $18,400 | Assumption, includes tax and insurance escrow |
| Late charges and lender legal fees | $4,000 (est.) | Estimate; ask for a reinstatement figure in writing |
| To reinstate | $22,400 (est.) | Missed payments plus fees |
| If you sell instead | ||
| Commission at 5% | -$27,325 (est.) | Negotiable |
| Conveyance tax, 0.75% state + 0.25% Shelton | -$5,465 | CGS 12-494 |
| Seller’s attorney | -$1,500 (est.) | Estimate |
| Full payoff (balance + arrears + fees) | -$332,400 (est.) | $310,000 + $22,400 |
| Left to you after a listed sale | about $179,810 (est.) | Before moving costs and the tax proration |
Shelton’s tax is about $5,930 a year on a $546,500 house, roughly $490 a month, far lower than in many Connecticut towns. That helps in mediation, where a modification is judged on whether the whole payment fits your income.
How much would you walk away with?
Slide the numbers to match your house. It works in your browser; nothing is saved or sent.
Estimates for planning. Conveyance tax per CGS 12-494 (state 0.75% up to $800,000, 1.25% to $2.5M, 2.25% above, plus the town rate). Seller attorney about $1,200 to $1,500; flat-fee MLS about $400; listings include three months of taxes, insurance and utilities, a cash sale about two weeks. Your attorney gives you the final numbers.
The lesson is not “sell”. If $22,400 is reachable or a modification fits, keeping the house is often better. If neither is, protect the equity before a judgment; see the consequences of foreclosure in Connecticut.
Should you prepare a sale while foreclosure mediation is still going?
You should prepare a sale while foreclosure mediation is still going if you are not sure a modification will work, because the mediation period ends after three sessions or seven months and the case then moves to judgment and a Law Day. Preparing means getting a payoff, a listing price and a written cash number. Nothing commits you, and a sale can still be one of the mediation outcomes.
Loan reviews take time, and many people only think about selling once a judgment motion is filed. A sale can itself be a mediation outcome, so learning your sale number costs nothing. The selling side, including how a sale stops the foreclosure at closing, is on our page about selling your house before foreclosure in Connecticut. For the whole process from summons to Law Day, see the Connecticut foreclosure guide.
What are the honest options for a Shelton homeowner, and when should you NOT sell to a cash buyer?
The honest options for a Shelton homeowner in foreclosure are to keep the house through reinstatement, a repayment plan or a modification; to list it with an agent; to sell it as-is for cash; or, if you owe more than it is worth, a short sale or deed in lieu. You should NOT sell to a cash buyer if mediation can give you an affordable payment, or if you have equity and enough months to list.
When you should NOT sell to a cash buyer
- Mediation can get you an affordable payment. Keep the house.
- You have equity and several months. In Shelton, a decent house usually sells on the open market; a listing will normally net more than any cash offer, including mine.
- You owe more than the house is worth. A cash buyer cannot fix that; the lender must approve a short sale.
- You have not filed for mediation or called free help. Do that first.
Is a cash sale right for you, or should you list?
Seven quick questions. There is no wrong answer, and we will tell you honestly if listing would leave you more.
- Does the house need repairs you would rather not pay for or manage?
- Do you need to close by a certain date, or within the next month or two?
- Would showings be hard: tenants, belongings, privacy, or you live out of state?
- Is there a complication: an estate or probate, a divorce, foreclosure, liens or back taxes?
- Could you comfortably cover the mortgage, taxes and utilities for three or more months?
- Is getting the highest possible price more important to you than speed and certainty?
- Would a buyer's bank lend on the house as it is (no major roof, foundation, oil tank or code issues)?
Where can a Shelton homeowner get free foreclosure help?
A Shelton homeowner can get free foreclosure help from the Judicial Branch’s Foreclosure Mediation Program, a HUD-approved housing counselor, the Connecticut Department of Banking foreclosure hotline, CHFA, and the Connecticut Fair Housing Center. None of them should charge you, and you should talk to at least one before signing anything with anyone, including us.
Call the Connecticut Department of Banking foreclosure hotline at 1-877-472-8313 or a HUD-approved housing counselor at 1-800-569-4287. If you have court papers, file for the Judicial Branch’s free Foreclosure Mediation Program within 15 days of the return date (jud.ct.gov/foreclosure). The Connecticut Fair Housing Center offers short attorney consultations at 1-888-247-4401. If your hardship is temporary, ask CHFA about its Emergency Mortgage Assistance Program at (860) 571-3500. Nobody legitimate charges an upfront fee to “save” your house or asks you to sign your deed over outside a closing with attorneys. Paid foreclosure or short sale negotiation in Connecticut requires a Department of Banking license unless done by your attorney (CGS 36a-671). See our page on we-buy-houses scams and red flags.
What should a Shelton homeowner do this week?
This week, a Shelton homeowner in foreclosure should find the return date, file the appearance and mediation certificate if the 15 days have not passed, call a free counselor, gather the documents on the checklist, ask the servicer for a written reinstatement figure and payoff, and get a realistic sale number in case keeping the house does not work.
Find the return date and count 15 days
It is on the summons. If you are inside the window, file JD-CL-12 and JD-CV-108 with the Ansonia-Milford clerk and send a copy to the lender’s attorney. If not, file JD-CV-96.
Call one free counselor
The Department of Banking hotline or a HUD-approved counselor. Ask them to review your budget before premediation.
Build the paperwork folder
Use the checklist above. Copy everything. Keep a call log.
Get two numbers in writing
A reinstatement amount and a full payoff, from the servicer. They tell you whether keeping and selling are possible.
Get a sale number as a backup
An agent’s price opinion and, if you want, a written as-is offer. If you sell to us: no fee, no repairs, no showings, a closing date you choose (typically about two weeks out), and no expiry while you finish mediation.
When you want a number for a Shelton house, our Shelton page is the place to start. If you would rather talk first, book a short call.
See the house together.
Pick a time that works.
Choose a time for us to walk through the property with you, or ask for a quick call first. We confirm every request personally.
Tuesday, January 13
No open times in the next few weeks. Please call us.
We will confirm by email. Nothing is booked until we do.
View my requestQuestions about foreclosure mediation in Shelton, CT
Which court handles a foreclosure on a Shelton house?
A foreclosure on a Shelton house is handled by the Superior Court for the Ansonia-Milford judicial district, which sits in Milford. Shelton is in Fairfield County, but for court purposes it belongs to Ansonia-Milford (CGS 51-344), and actions to foreclose a mortgage go to the district where the land is (CGS 51-345(b)).
Is foreclosure mediation in Connecticut free?
Yes, foreclosure mediation in Connecticut is free; the Judicial Branch charges no application fee.
Do I need a lawyer for foreclosure mediation in Shelton?
No, you do not need a lawyer for foreclosure mediation in Shelton. A free consultation through the Connecticut Fair Housing Center is still worth it.
Does mediation stop the foreclosure?
Mediation does not stop the foreclosure; it slows it. While mediation runs, most motions are frozen for up to eight months from the return date and no judgment can enter until the mediation period ends (CGS 49-31l(f)). The case continues afterward unless you reach an agreement.
How long does foreclosure mediation last in Connecticut?
Foreclosure mediation in Connecticut lasts until the third mediation session or seven months after the return date, whichever comes first (CGS 49-31n(a)). Either side or the mediator can ask the court to extend it with a JD-CV-96 motion.
What if I missed the 15-day deadline to request mediation?
If you missed the 15-day deadline, you can still ask a judge for permission by filing JD-CV-96 (Part I) with the mediation certificate and an appearance. The judge decides whether you are likely to benefit; file it as soon as you can.
Can I get mediation if my condo association or the town is foreclosing?
No, you cannot use the mediation program if your condo association or the town is foreclosing. The Judicial Branch says condominium-lien and tax-lien foreclosures are not eligible. Payment plans with the association or tax collector are the usual route.
Can I sell my Shelton house during foreclosure mediation?
Yes, you can sell your Shelton house during foreclosure mediation. A sale is one of the outcomes mediators discuss, and the lender is paid in full at closing. Tell the mediator and the lender’s attorney when you have a signed contract.
Related guides
Foreclosure stages
Other kinds of foreclosure
When you are ready to compare every route, start with how to sell a house in Connecticut, and if a sale is the answer, see selling before foreclosure.
Plain-English information, not legal advice. Talk to a Connecticut attorney or a HUD-approved counselor about your case. The Shelton example uses public data and labeled estimates.
Sources (checked on October 27, 2026)
- CGS chapter 846: 49-31k (definitions, eligibility), 49-31l (notice, 15 days, day-35 package, 8-month hold), 49-31n (mediation period).
- Connecticut Judicial Branch, Foreclosure Mediation Program homeowner FAQ (eligibility, what to bring, outcomes, condo and tax lien cases not eligible).
- Judicial Branch Foreclosure Mediation Program forms (JD-CL-12, JD-CV-108, JD-CV-96, JD-CV-136).
- CGS 51-344 and 51-345 (judicial districts; venue for foreclosures).
- CT OPM Real Estate Sales (data.ct.gov): Shelton sales October 2024 to September 2025.
- CT OPM mill rates (Shelton fiscal 2027: 15.51).
- CGS 12-494 (conveyance tax).
- Connecticut Department of Banking and CGS 36a-671 (foreclosure consultants).
- CHFA Emergency Mortgage Assistance Program.

Who wrote this
Jerryll Noorden
Jerryll has bought and sold Connecticut houses since 2016 and has sat at more closing tables than he can count, on both sides. Before real estate he was a robotics scientist at NASA, IHMC and IIT. He wrote this guide because the national sites that rank for it skip the Connecticut rules that cost sellers money. When listing or selling it yourself would get you more than a cash offer, he says so.
This guide explains Connecticut rules in plain English. It is not legal or tax advice. Laws change; for your sale, talk to a Connecticut real estate attorney and a tax professional.
