
Key facts at a glance
| Fact | Number | Source |
|---|---|---|
| Homes sold in Haddam, Oct 2024 to Sep 2025 | 106, median $441,500 (middle half $305,000 to $586,000) | CT OPM real estate sales, data.ct.gov |
| Single-family homes heated with oil | 78% | 2025 CT parcel (CAMA) data, data.ct.gov |
| Typical lot | Median 1.7 acres; about 79% of residential parcels are 1 acre or more | 2025 CT parcel (CAMA) data |
| Mill rate, fiscal 2027 | 24.98 (about $7,720 a year, $640 a month, on a $441,500 house, est.) | CT OPM mill rates, data.ct.gov |
| Conveyance tax the seller pays | 1.00% (0.75% state + 0.25% town) | CGS 12-494 |
| Court that hears a Haddam foreclosure | Middlesex Judicial District, 1 Court Street, Middletown | CGS 51-344(6), 51-346(a)(6); jud.ct.gov |
| Your deadline to sell or redeem | Law Day; a motion to extend must be granted before it passes | CGS 49-15 |
If your Haddam house is in foreclosure and you want to sell before you lose it, you have two real routes: list it with an agent, or sell it for cash. Which one works depends less on which pays more on paper and more on one number: how many weeks you have before Law Day. This guide puts the two side by side for a rural Middlesex County house, with Haddam numbers and a decision table by weeks left. It builds on our guide to how to sell a house in Connecticut and our Connecticut foreclosure guide.
Should you list or sell for cash to avoid foreclosure in Haddam?
To avoid foreclosure in Haddam, list the house if you have roughly four months or more before Law Day and it will pass a buyer’s inspection and appraisal; sell for cash if you have weeks, not months, or the house has well, septic, oil tank or repair issues a lender will flag. A listing usually nets more but takes about 15 weeks (est.); a cash sale typically closes in about two weeks.
Haddam is a quiet place to be in trouble. Big lots, long driveways, neighbors you wave to at the transfer station or along Route 154, and nobody who needs to know the house is in foreclosure. People here tell us they feel embarrassed, isolated, torn between holding out for full price and getting it over with, afraid of choosing wrong with no second chance, and tired of a house that keeps asking for oil, repairs and money.
Those are normal reactions to a real deadline. This page is for you if you want to sell to protect your equity and need to pick the route that will actually close in time. If you still hope to keep the house, the free-help box below comes first.
Call the Connecticut Department of Banking foreclosure hotline at 1-877-472-8313, or a HUD-approved housing counselor at 1-800-569-4287. Statewide Legal Services of Connecticut is at 1-800-453-3320, and the Connecticut Fair Housing Center offers foreclosure advice at 1-888-247-4401. If your case is recent, ask about the court’s free foreclosure mediation program (CGS 49-31l; forms at jud.ct.gov). None should charge you. Paid foreclosure or short sale negotiation requires a Department of Banking license unless your own attorney does it (CGS 36a-671).
A modification, reinstatement or refinance that keeps you in the house beats any sale. If those do not work, a sale before Law Day protects what you have built up; a strict foreclosure gives it to the lender. Our page on selling your house before foreclosure in Connecticut explains why.
How does a listing calendar compare with the foreclosure calendar?
A listing calendar compares badly with a foreclosure calendar when Law Day is close: preparing, marketing and closing with a mortgage buyer often takes about 15 weeks in total (est.), while the gap between a judgment and Law Day is often only about 6 to 13 weeks (est.). A cash sale takes about 2 weeks. If the listing would close after Law Day, the court must extend Law Day first (CGS 49-15).
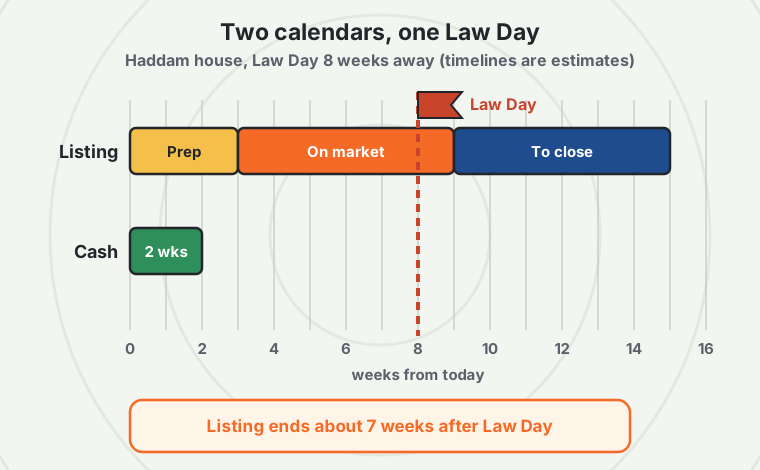
The listing side, with honest estimates for a Haddam single-family:
| Stage | Listing (est.) | Cash sale (est.) |
|---|---|---|
| Prepare: clean out, repairs, photos, well and septic paperwork | About 3 weeks | None; sold as is |
| On the market until an accepted offer | About 6 weeks; longer for a house needing work | A written offer within days |
| Contract to closing: inspection, well test, appraisal, mortgage | About 6 weeks | About 2 weeks |
| Total | About 15 weeks | About 2 weeks |
The foreclosure side is set by the court. After the judgment, the court sets Law Days, often 45 to 90 days out in practice (est.), and the owner’s Law Day is the last day to redeem. A motion to open and extend Law Day can buy time if you have a good reason, like a signed contract, but it has to be heard and granted before Law Day; how those motions work is covered in our guide to Law Day in Connecticut. Haddam cases are heard in the Middlesex Judicial District in Middletown.
Why do wells, septic systems and oil tanks matter so much for a Haddam sale?
Wells, septic systems and oil tanks matter for a Haddam sale because a buyer with a mortgage usually tests or inspects them before closing, and a failed water test, a septic problem or a buried oil tank can delay or kill the deal. In Haddam, 78% of single-family homes heat with oil and the median lot is 1.7 acres, so these systems are common, and each test adds days to a listing calendar.
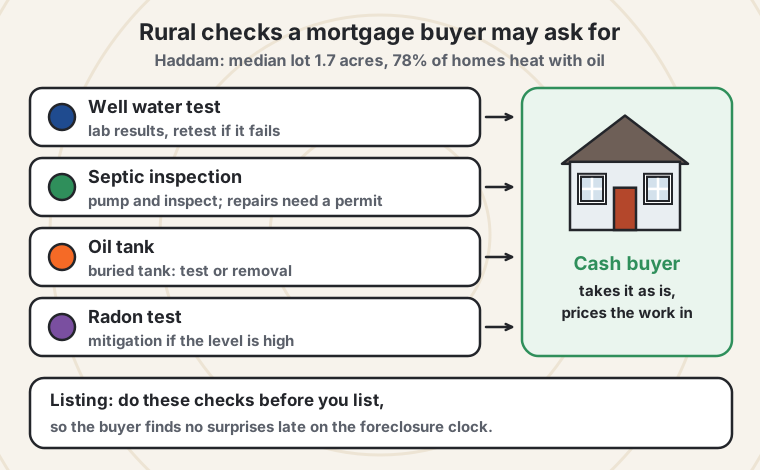
Here is what a mortgage buyer’s side typically asks for, and why it matters on a foreclosure clock:
- Private well. Buyers and many lenders want a water test (bacteria and often more). Results take days, and a failed test means treatment and a retest. Connecticut does not appear to require a well test at every sale, but buyers usually ask for one.
- Septic. A buyer’s inspector may pump and inspect the tank and leach field. A failing field can mean a costly repair and a permit from the local health office before anyone will lend.
- Oil tank. With 78% of single-family homes on oil, many Haddam houses have a tank in the basement or, in older homes, buried in the yard. Buyers and insurers often want a buried tank tested or removed.
- Radon. A radon test is common in a Connecticut inspection; mitigation is usually manageable but adds a step.
You also owe the buyer the Connecticut property condition disclosure report, which asks about the well, septic and heating system, or a $500 credit at closing if you do not provide it (CGS 20-327b, 20-327c), plus a signed smoke and carbon monoxide affidavit at closing (CGS 29-453). Our guide to oil tanks, septic, wells and radon when selling in Connecticut covers each test, costs and who pays.
None of this stops a listing. It just means a Haddam listing in foreclosure needs these checks done early, before you list, so the buyer’s inspection holds no surprises.
How much would you keep each way? A Haddam example
How much you keep each way depends on the price, the payoff on closing day and your selling costs. In the illustrative Haddam example below, a listing at the town median keeps about $55,987 if the court extends Law Day and the sale closes, a cash sale two weeks out keeps about $38,164, and a strict foreclosure keeps nothing.
Example (illustrative). A Haddam Colonial worth about the town’s median of $441,500, with a $340,000 judgment (including $320,000 principal at 6%, so interest runs at about $52.60 a day). Law Day is 8 weeks away.
| Line | Cash sale, closes in 2 weeks | Listing, closes in about 15 weeks |
|---|---|---|
| Price | $385,000 (illustrative offer) | $441,500 (town median) |
| Judgment amount | -$340,000 | -$340,000 |
| Interest after judgment | -$736 (14 days) | -$5,523 (105 days) |
| Later lender fees (est.) | -$750 | -$2,000 (incl. a motion to extend) |
| Commission (5%, est.) | $0 | -$22,075 |
| Conveyance tax, 1.00% | -$3,850 | -$4,415 |
| Your attorney (est.) | -$1,500 | -$1,500 |
| Prep, well, septic and tank items (est.) | $0 | -$10,000 |
| You keep | $38,164 | $55,987, only if Law Day is extended about 7 weeks and the buyer closes |
On paper the listing wins by about $17,823. But this listing closes 7 weeks after Law Day, so it only works if the court extends Law Day and nothing in the well, septic or appraisal stage slips. If Law Day passes, the owner keeps $0 of the roughly $100,000 gap between the median value and the judgment. The honest way to read the table: the listing number is a possibility, the cash number is the floor you can count on in time, and the foreclosure number is what happens if neither closes.
Run your own numbers:
How much would you walk away with?
Slide the numbers to match your house. It works in your browser; nothing is saved or sent.
Estimates for planning. Conveyance tax per CGS 12-494 (state 0.75% up to $800,000, 1.25% to $2.5M, 2.25% above, plus the town rate). Seller attorney about $1,200 to $1,500; flat-fee MLS about $400; listings include three months of taxes, insurance and utilities, a cash sale about two weeks. Your attorney gives you the final numbers.
Which route fits how many weeks you have left before Law Day?
The route that fits depends on the weeks left before Law Day: with 16 or more weeks, listing is realistic; with 10 to 16, list only a market-ready house and keep a cash backup; with 6 to 10, a listing needs a court extension; under 6 weeks, a cash sale or redemption is usually the only sale that closes in time. These bands are estimates, not rules.
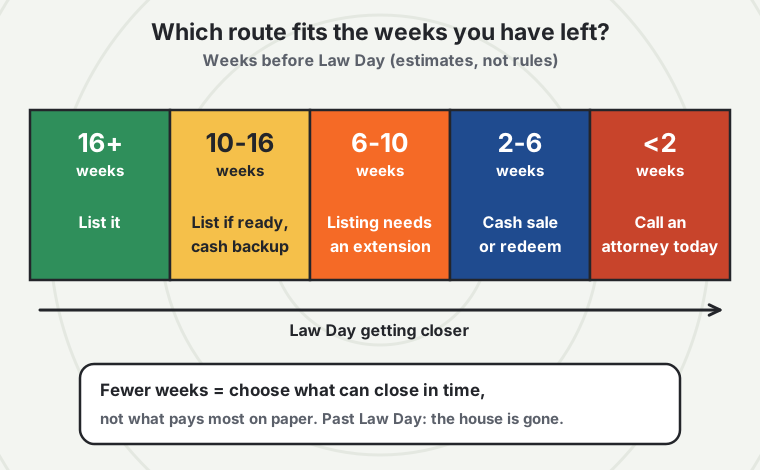
| Weeks before Law Day | What usually works | Watch out for |
|---|---|---|
| 16 or more | List with an agent; price to sell in the first few weeks | Do the well, septic and tank checks before listing |
| 10 to 16 | List only if the house is market-ready; get a written cash offer as a backup | Favor buyers with strong financing; plan a motion to extend early |
| 6 to 10 | Cash sale, or a listing that sells fast plus a motion to extend with the signed contract | A financed buyer’s loan or appraisal slipping past Law Day |
| 2 to 6 | Cash sale, refinance or redemption | Title issues; order the payoff the day you sign (CGS 49-10a) |
| Under 2 | Call an attorney today; a motion must be heard before Law Day | Anyone promising to “stop” Law Day for a fee |
| Law Day passed | The house is the lender’s | See what happens next in our guide to life after Law Day |
Is a cash sale right for you, or should you list?
Seven quick questions. There is no wrong answer, and we will tell you honestly if listing would leave you more.
- Does the house need repairs you would rather not pay for or manage?
- Do you need to close by a certain date, or within the next month or two?
- Would showings be hard: tenants, belongings, privacy, or you live out of state?
- Is there a complication: an estate or probate, a divorce, foreclosure, liens or back taxes?
- Could you comfortably cover the mortgage, taxes and utilities for three or more months?
- Is getting the highest possible price more important to you than speed and certainty?
- Would a buyer's bank lend on the house as it is (no major roof, foundation, oil tank or code issues)?
If you list a Haddam house in foreclosure, how do you make it close in time?
If you list a Haddam house in foreclosure, make it close in time by telling your agent your Law Day on day one, doing the well, septic and oil tank checks before listing, pricing to sell in the first weeks, choosing the offer with the surest financing and a closing date before Law Day, and having your attorney ready to move to extend Law Day with the contract attached.
- Give your agent the Law Day date in writing and ask for a marketing plan that fits it.
- Order a water test and a septic inspection before listing, and gather any oil tank records.
- Price at or slightly under the market, not above it; a price cut in week 5 costs more weeks than it saves.
- Prefer cash or strong conventional financing over offers with long contingencies.
- Ask your attorney to request the payoff the day a contract is signed (CGS 49-10a).
- Keep a written cash offer in your back pocket; if the first buyer fails in week 10, there may be no time for a second.
An agent who has sold houses with a foreclosure on title knows the paperwork; ask about it in the interview. Our guide on selling a house during an open foreclosure explains the payoff, the lender’s attorney’s fees and how the case is withdrawn after closing.
When should you NOT sell your Haddam house to a cash buyer?
You should not sell your Haddam house to a cash buyer if you can keep it through a modification or refinance, if you have four months or more before Law Day and the house is ready for the market, or if the cash offer does not leave you clearly more certainty for a price you can accept. In those cases a listing, or keeping the house, is usually the better choice.
Haddam homes are larger and newer than in many Connecticut towns (median year built 1972), and a well-kept Colonial or Ranch on a good lot sells to buyers with mortgages. If that is your house and you have the time, list it. If listing nets you more and you have time, we will tell you so. A cash sale earns its discount when the calendar is short, the house needs work or system repairs a lender will flag, or the house is vacant and costing you oil and taxes every month. If the house is worth less than you owe, neither route works without the lender’s approval; see our short sale guide. More on the trade-off in why cash offers are lower.
How do you sell a Haddam house to avoid foreclosure, step by step?
To sell a Haddam house to avoid foreclosure, get free advice, find your Law Day and payoff, count the weeks, get a listing estimate and a cash offer in writing, pick the route that closes before Law Day, sign with your own attorney, and close with the lender paid in full. A cash sale typically closes in about two weeks.
Get free advice
Department of Banking hotline or a HUD-approved counselor, to make sure keeping the house is not possible.
Count your weeks
Find your Law Day on the judgment, and ask your attorney for a written payoff (CGS 49-10a).
Get two numbers
A listing estimate from a local agent and a written cash offer. For a no-obligation number, use our Haddam page; no fees, and the offer does not expire while you compare.
Pick the route that closes in time
Use the weeks table above. If the closing lands after Law Day, your attorney moves to extend with the contract attached (CGS 49-15).
Close and confirm
The lender is paid from the sale, the case is withdrawn, and the rest is yours. With a cash buyer, leave what you do not want.
Frequently asked questions
Can I sell my house to avoid foreclosure in Haddam, CT?
Yes, you can sell your house to avoid foreclosure in Haddam, CT, any time before your Law Day. The lender’s payoff is paid from the sale, the foreclosure is withdrawn, and you keep the rest.
Which court handles a Haddam foreclosure?
A Haddam foreclosure is handled by the Superior Court for the Middlesex Judicial District, at 1 Court Street in Middletown (CGS 51-344, 51-346).
How long does it take to sell a house in Haddam with an agent?
Selling a house in Haddam with an agent often takes about 15 weeks from preparing to closing (est.), including about 6 weeks for a mortgage buyer to close. A house that needs work or has well, septic or tank issues can take longer.
Is listing or a cash sale better before Law Day?
Listing is usually better before Law Day if you have about four months or more and a market-ready house; a cash sale is usually better if you have weeks, not months, or the house needs work a lender will flag.
Do I need a well test to sell a house in Haddam?
You may not be legally required to test the well to sell a house in Haddam, but most buyers and many lenders ask for a water test, so plan for one if you list.
What is the conveyance tax in Haddam?
The conveyance tax in Haddam is 1.00% of the price for most homes: 0.75% to the state and 0.25% to the town, paid by the seller (CGS 12-494). On a $441,500 sale it is $4,415.
Can the court give me more time to sell?
The court can give you more time to sell if your attorney files a motion to open and extend Law Day and the court grants it before Law Day (CGS 49-15). A signed contract with a closing date is the best support.
What are Haddam property taxes on a median house?
Haddam property taxes on a $441,500 house are about $7,720 a year, or about $640 a month, at the fiscal 2027 mill rate of 24.98 on a 70% assessment (est.).
Will a cash buyer take a house with a buried oil tank or a failing septic?
Yes, a cash buyer will usually take a house with a buried oil tank or a failing septic system as is, and price the work into the offer instead of asking you to fix it first.
Related guides
The foreclosure case
Selling before Law Day
For the whole selling process, see how to sell a house in Connecticut, and for how a sale before foreclosure works with us, our foreclosure sale page. To talk it through, call me, Jerryll Noorden, at (203) 529-4712. I have bought Connecticut houses since 2016, about ten a year.
Plain-English information, not legal advice. Talk to a Connecticut attorney about your own case.
Sources (checked on October 27, 2026)
- CGS chapter 846: 49-10a (payoff statements), 49-15 (opening and extending strict foreclosure judgments), 49-31l (mediation).
- CGS 51-344 and 51-346 (judicial districts and court locations) and Middlesex Judicial District location.
- CGS 12-494 (conveyance tax).
- CGS 20-327b and 20-327c (property condition report) and CGS 29-453 (smoke and carbon monoxide affidavit).
- CGS 36a-671 (licensing of debt negotiation, including short sale negotiation).
- CT Department of Banking: avoiding foreclosure and Judicial Branch foreclosure resources.
- CT OPM Real Estate Sales (Haddam, Oct 2024 to Sep 2025), 2025 CT Parcel and CAMA data and OPM mill rates, fiscal 2027.
See the house together.
Pick a time that works.
Choose a time for us to walk through the property with you, or ask for a quick call first. We confirm every request personally.
Tuesday, January 13
No open times in the next few weeks. Please call us.
We will confirm by email. Nothing is booked until we do.
View my request
Who wrote this
Jerryll Noorden
Jerryll has bought and sold Connecticut houses since 2016 and has sat at more closing tables than he can count, on both sides. Before real estate he was a robotics scientist at NASA, IHMC and IIT. He wrote this guide because the national sites that rank for it skip the Connecticut rules that cost sellers money. When listing or selling it yourself would get you more than a cash offer, he says so.
This guide explains Connecticut rules in plain English. It is not legal or tax advice. Laws change; for your sale, talk to a Connecticut real estate attorney and a tax professional.
