
Key facts at a glance
| Fact | Number | Source |
|---|---|---|
| Homes sold in Rocky Hill, Oct 2024 to Sep 2025 | 233, of which 125 condos (54%) | CT OPM real estate sales, data.ct.gov |
| Median sale price | Condo $290,000; single-family $425,000 | CT OPM real estate sales, data.ct.gov |
| Condo units in town | 2,585; median year built 1983; median 1,185 sq ft; 83% natural gas heat | 2025 CT parcel (CAMA) data, data.ct.gov |
| Mill rate, fiscal 2027 | 31.7 (about $536 a month on a $290,000 condo) | CT OPM mill rates, data.ct.gov |
| Conveyance tax the seller pays | 1.00% up to $800,000 (0.75% state + 0.25% town) | CGS 12-494 |
| Resale certificate from the association | Due within 10 business days of your request; base fee $185, adjusted for inflation | CGS 47-270(b); CGS 47-213 |
| Buyer’s right to cancel after getting the certificate | Until 5 business days after delivery (7 if mailed), or closing | CGS 47-270(c) |
| Probate court and Superior Court | Probate district for Newington, Rocky Hill and Wethersfield; New Britain Judicial District | CGS 45a-2; CGS 51-344 |
In Rocky Hill, more than half of all home sales are condos. Selling one for cash works differently from selling a house: the association has to produce a resale certificate, unpaid dues and special assessments come off your proceeds, and whether a buyer can get an FHA loan in your complex can decide whether you need a cash buyer at all. This guide covers all three and runs the cash-offer math on Rocky Hill’s $290,000 condo median. It is part of our guide to how to sell a house in Connecticut.
How do you sell a condo for cash in Rocky Hill, CT?
To sell a condo for cash in Rocky Hill, CT, request the resale certificate from your association right away (it is due within 10 business days under CGS 47-270), find out your dues, any special assessment and any unpaid balance, get written offers from two or three cash buyers, and close through attorneys. On Rocky Hill’s $290,000 condo median needing light work, a cash buyer’s formula gives about $213,500.
A cash sale skips the parts of a condo sale that most often go wrong: the buyer’s lender reviewing the association’s budget and insurance, the appraisal, and the question of whether the complex is approved for FHA loans. What it does not skip is the association paperwork and the money owed to the association, which a cash buyer will want settled at closing like any other buyer. The full cash-offer formula is explained in our pillar on cash home buyers in Connecticut; below we apply it to a Rocky Hill condo.
Why does selling a Rocky Hill condo feel more complicated than selling a house?
Selling a Rocky Hill condo feels more complicated than selling a house because part of the sale is out of your hands. The association controls the paperwork, decides the special assessments, and its budget and insurance can affect whether a buyer’s bank will lend. You can do everything right with your own unit and still be held up by the complex.
Maybe you are downsizing again, or moving closer to family, and the unit you bought in the 1980s needs a new kitchen and carpet. Maybe a parent’s condo is now part of an estate and the monthly dues keep coming. Maybe the association just announced a roof or siding assessment, and you would rather not be the one paying it. You may feel frustrated with the association, anxious about a sale falling through over paperwork, stuck paying dues on an empty unit, worried that a cash buyer will take advantage, and tired of the whole thing.
Each of those worries has a concrete answer, and most of them are in Connecticut’s condo law. This page is for you.
What is the resale certificate, and how long does it take in Connecticut?
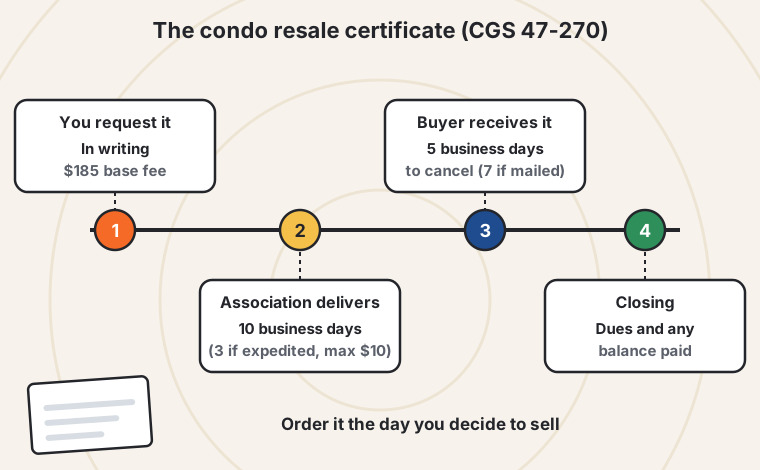
The resale certificate is a package your condo association must prepare when you sell, listing your monthly dues, anything you owe, approved capital spending over $1,000, the reserves, the budget, insurance, pending lawsuits and other facts a buyer needs (CGS 47-270). The association must deliver it within 10 business days of your written request and payment of a $185 base fee, adjusted for inflation. You hand it to the buyer before closing.
| Step | Rule | Statute |
|---|---|---|
| You request the certificate in writing and pay | Base fee $185, adjusted for inflation, plus copy costs or a $10 electronic fee; no attorney or paralegal charges allowed in the fee | CGS 47-270(b)(1); 47-213 |
| The association prepares it | Within 10 business days; within 3 business days if you pay an expedite fee of no more than $10 | CGS 47-270(b)(1) |
| You give it to the buyer or their attorney | With the declaration, bylaws and rules, before closing or before the buyer takes possession | CGS 47-270(a) |
| The buyer may cancel | Until 5 business days after delivery (7 if sent by certified or registered mail), or closing, whichever comes first | CGS 47-270(c) |
| Wrong numbers on the certificate | The buyer is not liable for unpaid assessments above the certificate’s amounts; you are not liable for the association’s errors | CGS 47-270(b)(2) and (c) |
The certificate matters in a cash sale for a practical reason: the buyer prices what it says. If it shows a large approved capital project, low reserves, many owners behind on their dues, or a lawsuit against the association, the buyer will lower the offer or ask you to cover part of it. Order it early so you see what the buyer will see. You still owe the buyer Connecticut’s property condition report too, or a $500 credit at closing (CGS 20-327b and 20-327c); our disclosure guide explains it.
How do HOA dues and special assessments affect a cash offer in Rocky Hill?
HOA dues and special assessments affect a cash offer in Rocky Hill in two ways. Monthly dues are a holding cost the buyer counts for every month they own the unit before reselling or renting, so higher dues mean a lower offer. A special assessment that is approved but unpaid is a debt someone must pay; either you pay it at closing or the buyer takes it over and lowers the price by about that amount.
Connecticut gives the association strong collection rights. Its lien for unpaid assessments ranks ahead of most other liens, and in a foreclosure it can come ahead of the first mortgage for up to nine months of regular dues (CGS 47-258). In a sale, that means any balance you owe the association is paid from your proceeds at closing, just like your mortgage payoff.
- Who pays a special assessment is negotiable. The contract should say whether you pay the full assessment, only the installments due before closing, or nothing. A typical arrangement is that the seller pays what is due before closing and the buyer takes over later installments, but nothing in the statute requires that; it is in the contract.
- Dues above the norm for similar complexes reduce what any buyer will pay, cash or financed.
- Arrears in the complex. The certificate must state how many owners are 60 or more days behind (CGS 47-270(a)(14)). High numbers can worry lenders and buyers alike.
Why does FHA condo approval matter when you sell a Rocky Hill condo?
FHA condo approval matters when you sell a Rocky Hill condo because many first-time buyers and downsizers use FHA loans, and FHA will only insure a loan in a complex that is approved or that qualifies for a single-unit approval. If your complex is not approved and does not qualify, those buyers cannot use FHA, your buyer pool shrinks, and a cash buyer becomes more relevant.
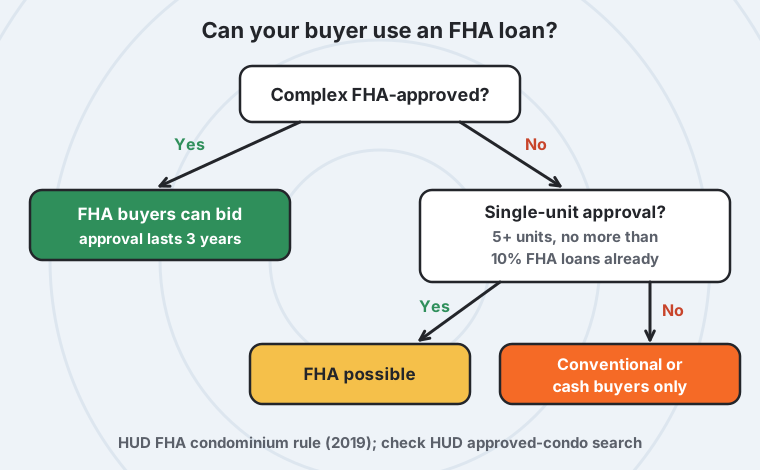
You can look up your complex on HUD’s approved-condominium search. Under the FHA condo rule that took effect in 2019:
- Project approval lasts three years, after which the association must recertify.
- Single-unit approval lets FHA insure a loan on one unit in a complex that is not approved, if the complex has at least five units and, for projects of 10 or more units, no more than 10% of units already have FHA-insured loans.
- Owner occupancy generally needs to be at least 50% of units, with some exceptions down to 35%.
Conventional lenders have their own condo reviews; a complex with pending litigation, low reserves or a high share of owners behind on dues can be hard to finance with any loan. If your complex has those problems, a cash buyer may be the most reliable route. If it does not, a listing probably nets more, as the math below shows. For broader context, see how appraisals affect a Connecticut sale.
What would a cash buyer pay for a Rocky Hill condo?
A cash buyer would pay about $213,500 for a Rocky Hill condo worth $290,000 once refreshed that needs $12,000 of light work, in this illustration: about 74% of the finished value. Dues, property tax, financing and the costs of reselling make up the rest of the gap with the buyer’s margin. A pending special assessment would come off on top, roughly dollar for dollar.

| Line | Amount | How it was figured |
|---|---|---|
| After-repair value | $290,000 | Rocky Hill’s median condo sale, Oct 2024 to Sep 2025 |
| Repairs | -$12,000 | Flooring, paint, kitchen refresh (est.) |
| Resale commission (5%) | -$14,500 | (est.) |
| Conveyance tax on the resale (1.00%) | -$2,900 | 0.75% state + 0.25% town (CGS 12-494) |
| Resale attorney and purchase closing | -$3,700 | $1,200 and $2,500 (est.) |
| Property tax, 3 months | -$1,608 | $536 a month: 31.7 mills on 70% of $290,000 |
| Dues, insurance and utilities, 3 months | -$1,950 | $650 a month, including $350 dues (assumption) |
| Interest at 11% and 2 points | -$10,717 | On about $225,600 borrowed (est.) |
| Margin (10%) | -$29,000 | (est.) |
| Formula offer | About $213,500 | About 74% of the finished value |
| What you net | List it | Sell for cash |
|---|---|---|
| Price | $290,000 | $213,500 |
| Commission (5%, est.) | -$14,500 | $0 |
| Conveyance tax (1.00%) | -$2,900 | -$2,135 |
| Your attorney (est.) | -$1,200 | -$1,200 |
| Resale certificate (base fee) | -$185 | -$185 |
| Carrying while listed, 2 months (tax $536, dues $350, utilities $100, est.) | -$1,972 | $0 |
| Net before mortgage payoff | $269,243 | $209,980 |
The gap of about $59,000 is the honest cost of a cash sale on a condo that a financed buyer could buy. Our explainer on why cash offers are so low breaks down each part of it, and the statewide comparison of a cash buyer vs. a realtor shows the same trade-off for houses.
How much would you walk away with?
Slide the numbers to match your house. It works in your browser; nothing is saved or sent.
Estimates for planning. Conveyance tax per CGS 12-494 (state 0.75% up to $800,000, 1.25% to $2.5M, 2.25% above, plus the town rate). Seller attorney about $1,200 to $1,500; flat-fee MLS about $400; listings include three months of taxes, insurance and utilities, a cash sale about two weeks. Your attorney gives you the final numbers.
When should you not sell your Rocky Hill condo for cash?
You should not sell your Rocky Hill condo for cash when the complex is FHA-approved or otherwise easy to finance, the unit is in decent shape, there is no large assessment pending, and you can wait a couple of months. Rocky Hill condos sell often, 125 in a year, so a well-priced unit in a financeable complex usually nets more on the open market.
Cash makes more sense when the complex cannot be financed (no FHA approval, litigation, weak reserves), when a large special assessment would scare off financed buyers, when the unit needs more than cosmetic work, when an estate is paying dues on an empty unit, or when a tenant is in place. For the estate case, see selling an inherited house or condo in Connecticut; for a tenant, see selling a rental with tenants.

With a condo, the first thing I ask for is the association’s contact and the last budget. Order the resale certificate the same day you decide to sell. It costs little, and it is the document that most often decides whether a closing happens on time.
What are the steps to sell a Rocky Hill condo for cash?
The steps to sell a Rocky Hill condo for cash are: request the resale certificate, gather your dues, assessment and payoff figures, get two or three written cash offers, agree in the contract who pays any assessment, and close through attorneys. With the certificate in hand and a clear title, a cash sale typically closes in about two weeks.
Request the resale certificate
In writing, to the association or its manager, with the fee. Ask for the expedited version if your closing is close.
Know what you owe
Your mortgage payoff, any unpaid dues or fines, and any special assessment, including installments not yet due.
Get written offers
Show each buyer the certificate. Ask what dues, repair and resale figures they used.
Settle the assessment in the contract
Who pays which installments, and how it shows up on the closing statement.
Close through attorneys
Your attorney pays off the association and the mortgage, files the conveyance tax return, and you sign the smoke and carbon monoxide detector affidavit at closing (CGS 29-453; the old $250 credit option was removed).
If you want a number on your unit, our Rocky Hill page is the place to start. We buy condos and houses in nearby towns too, including Wethersfield, Newington and Cromwell.
Questions about selling a condo for cash in Rocky Hill
Can I sell a condo for cash in Rocky Hill, CT?
You can sell a condo for cash in Rocky Hill, CT the same way as a house, with one extra step: the association’s resale certificate under CGS 47-270. A cash sale removes the buyer’s lender review of the complex.
How long does a Connecticut condo resale certificate take?
A Connecticut condo resale certificate must be delivered within 10 business days of your written request and payment, or within 3 business days if you pay an expedite fee of no more than $10 (CGS 47-270(b)).
How much does a resale certificate cost in Connecticut?
A resale certificate in Connecticut costs a base fee of $185, adjusted for inflation under CGS 47-213, plus copy costs or a $10 electronic fee. The fee may not include attorney or paralegal costs. Ask your association for its current amount.
Who pays a special assessment when a condo is sold?
Who pays a special assessment when a condo is sold depends on the contract. Often the seller pays installments due before closing and the buyer takes over the rest, but a cash buyer will usually lower the price to match whatever they take on.
Can a buyer back out after getting the resale certificate?
A buyer can back out of a Connecticut condo purchase until 5 business days after receiving the resale certificate (7 if mailed), or until closing, whichever comes first (CGS 47-270(c)).
What if my Rocky Hill condo complex is not FHA-approved?
If your Rocky Hill complex is not FHA-approved, an FHA buyer may still get a single-unit approval in some complexes. If not, your buyers are conventional and cash buyers, which can lower your price and make a cash sale more relevant.
Do I pay unpaid HOA dues at closing?
You pay unpaid HOA dues at closing from your proceeds. The association’s lien ranks ahead of most other liens (CGS 47-258), so no buyer’s attorney will close without it being paid.
What is the conveyance tax on a Rocky Hill condo sale?
The conveyance tax on a Rocky Hill condo sale is 1.00% of the price up to $800,000: 0.75% state and 0.25% town (CGS 12-494). On a $290,000 sale that is $2,900, paid by the seller.
Is selling a condo for cash worth it?
Selling a condo for cash is worth it when financing is the problem: an unapproved complex, litigation, a big assessment or a unit that needs real work. In a financeable complex, listing nets about $59,000 more in our $290,000 example.
Related guides
The offer
Other towns, other angles
For every route and step, see how to sell a house in Connecticut. For a no-obligation number on a Rocky Hill condo or house, visit our Rocky Hill page.
Plain-English information, not legal advice. Your association documents and a Connecticut attorney control the details of your sale.
Sources (checked on October 27, 2026)
- Connecticut OPM Real Estate Sales (Rocky Hill, recorded Oct 2024 to Sep 2025, residential sales of $30,000 or more), data.ct.gov.
- OPM mill rates, fiscal 2027, data.ct.gov.
- 2025 Connecticut Parcel and CAMA Data (Rocky Hill condo units, year built, heating fuel), data.ct.gov.
- CGS 47-213, 47-258 and 47-270 (Common Interest Ownership Act: fee adjustment, association lien, resale certificate).
- CGS 12-494 (conveyance tax).
- CGS 20-327b and 20-327c (property condition report, $500 credit).
- CGS 29-453 (smoke and carbon monoxide detector affidavit).
- CGS 45a-2 (probate districts) and CGS 51-344 (judicial districts).
- HUD: FHA condominium rule (2019) and HUD approved condominium search.
See the house together.
Pick a time that works.
Choose a time for us to walk through the property with you, or ask for a quick call first. We confirm every request personally.
Tuesday, January 13
No open times in the next few weeks. Please call us.
We will confirm by email. Nothing is booked until we do.
View my request
Who wrote this
Jerryll Noorden
Jerryll has bought and sold Connecticut houses since 2016 and has sat at more closing tables than he can count, on both sides. Before real estate he was a robotics scientist at NASA, IHMC and IIT. He wrote this guide because the national sites that rank for it skip the Connecticut rules that cost sellers money. When listing or selling it yourself would get you more than a cash offer, he says so.
This guide explains Connecticut rules in plain English. It is not legal or tax advice. Laws change; for your sale, talk to a Connecticut real estate attorney and a tax professional.
